🎓 Trusted by 10,000+ Students Across India
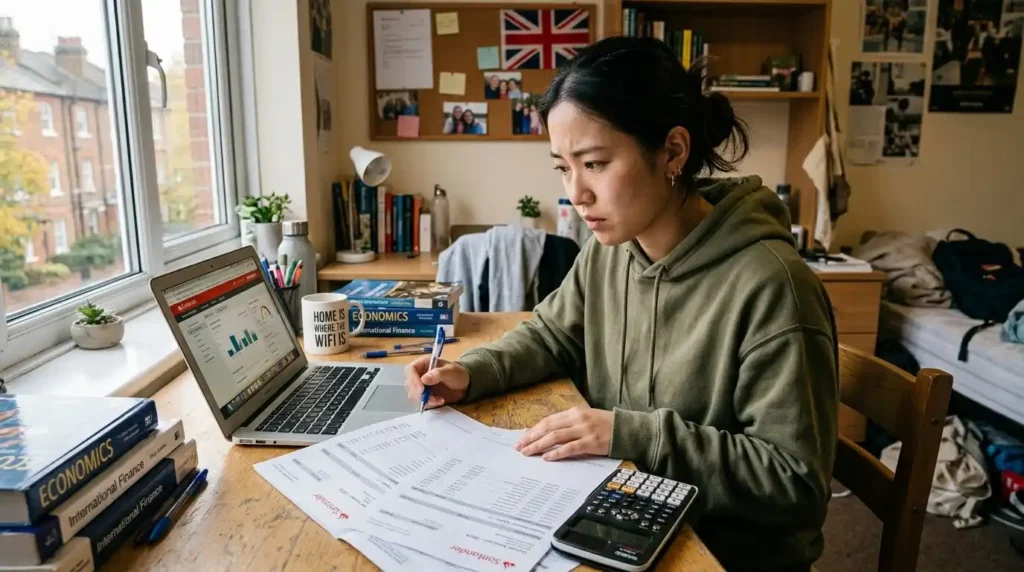
Most study abroad financial assistance content focuses entirely on the period before departure, comparing loans, applying for scholarships, calculating the total cost of attendance. Almost none of it addresses what happens if, six or twelve months into the course, the numbers stop adding up. A weaker rupee, an unexpected medical expense, a rent increase, or simply underestimating living costs at the outset can all create a real funding gap while you’re already abroad, with far fewer options available in the moment than you had before leaving.
This guide focuses specifically on that situation: what genuine study abroad financial assistance looks like once you’re already mid-course and money is tighter than planned.
Even careful pre-departure budgeting can fall short once real life abroad begins. Currency fluctuation is one of the most common culprits: a rupee that weakens meaningfully against the dollar, pound, or euro over a year can add a noticeable gap to a budget that looked comfortable when the loan was first sanctioned.
Underestimating living costs is another frequent cause, particularly for students who budgeted based on shared or on-campus accommodation but ended up needing private rental, or who didn’t fully account for a mandatory health insurance renewal. One-time shocks, a medical emergency, an unplanned flight home, or a laptop replacement, can also tip an otherwise adequate budget into a genuine shortfall.
Before assuming you need additional external funding, revisit your actual monthly spending against your original budget to understand the real size of the gap, not just a general sense that money feels tight. Often the shortfall is smaller and more specific than it initially feels, tied to one or two categories like rent or insurance rather than a broad, unmanageable overspend.
Contact your university’s financial aid or international student office early. Many universities maintain emergency financial assistance funds specifically for international students facing an unexpected shortfall, and these are frequently underused simply because students don’t think to ask, assuming such support is reserved for domestic students only.
If your shortfall is tied to genuine cost increases rather than overspending, many lenders offer a top-up facility on an existing education loan, allowing you to borrow an additional amount without restructuring the entire loan from scratch. This is often more straightforward than applying for a completely new loan, since your lender already has your academic and financial history on file.
Reach out to your original lender directly to understand their top-up process and required documentation, which usually includes an updated cost estimate from your university reflecting the actual increase you’re facing. If your original loan was a secured education loan, a top-up against the same collateral is often processed faster than a fresh application would be.
If your original loan’s interest rate is now noticeably higher than current market rates, or if a better lender option has become available since you first borrowed, exploring refinancing or a balance transfer mid-course can sometimes free up enough monthly cash flow to address a shortfall without needing additional borrowing at all. This is worth evaluating even if your immediate concern is a funding gap rather than the interest rate itself, since the two are often connected.
Many study visas allow a limited number of part-time work hours during term time, which can help offset a moderate shortfall, though it’s rarely enough to cover a significant gap entirely on its own. Check your specific visa’s work hour restrictions carefully before relying on this as a primary solution, since exceeding permitted hours can create serious visa complications that far outweigh the financial benefit.
Part-time work tends to work best as a supplement to other forms of study abroad financial assistance rather than a standalone fix for a substantial shortfall, particularly during the first semester when adjusting to coursework already takes significant time and energy.
Some scholarships, particularly smaller, less publicized ones, remain open for application even after a course has started, especially those tied to specific departments or ongoing academic performance rather than initial admission. It’s worth checking with your university’s scholarship office directly, since these opportunities are easy to miss if you assumed all scholarship applications had to happen before enrollment.
Separately, checking whether any scholarship assistance programs you were initially eligible for back in India have a supplementary or emergency component is also worth a quick follow-up, since some schemes do offer additional support in genuine hardship situations.
Whatever the cause of the shortfall, addressing it early gives you meaningfully more options than waiting until the situation becomes urgent. A lender is generally more willing to discuss a top-up or a temporary adjustment when approached proactively, with a clear explanation of the gap, than when a payment is already overdue or a crisis has developed.
Similarly, keeping your family informed as soon as you notice a gap forming, rather than after it’s become severe, allows for calmer, more considered decisions about whether a top-up loan, family contribution, or part-time work is the right combination for your specific situation.
Many students wait too long before addressing a shortfall, hoping it will resolve itself, which usually only makes the eventual gap larger and harder to close. Others turn immediately to high-interest short-term borrowing options in the host country without first checking whether a top-up on their existing education loan would be both cheaper and faster to arrange.
Some students avoid contacting their university’s financial aid office, assuming emergency support is only for domestic students, missing a resource that’s often genuinely available to international students as well. A frequent mistake is not communicating with family or the original lender until the situation has become urgent, narrowing the range of calm, well-considered options that were available earlier.
Track your actual spending against your original budget monthly, not just when something feels obviously off, so you catch a forming gap early rather than after it’s become significant. Contact your university’s international student office proactively to understand what emergency financial resources exist, even if you don’t currently need them, so you know the process in advance if a shortfall does develop.
If a top-up on your existing loan seems likely, reach out to your original lender as soon as you identify the gap, since earlier requests are generally processed more smoothly than urgent, last-minute ones. Keep your family looped in throughout, since decisions made calmly and early tend to produce better outcomes than reactive ones made under pressure.
Study abroad financial assistance shouldn’t stop being relevant once you’ve boarded your flight. Mid-course shortfalls happen more often than pre-departure planning usually accounts for, whether from currency shifts, underestimated living costs, or genuine emergencies, and knowing your options in advance, loan top-ups, university emergency funds, refinancing, and limited part-time work, makes a real difference in how manageable these situations feel when they arise.
Addressing a gap early and communicating proactively with your lender, university, and family consistently leads to better outcomes than waiting until the shortfall has become a genuine crisis.
Facing a funding gap while already studying abroad? Book a free consultation with Loan Scholar and get help exploring a top-up, refinancing, or the right next step for your specific situation.
Book a free consultation and get clarity on your loan journey today.
© 2026 Loan Scholar . All Rights Reserved.Designed, Developed & Marketed by
SDS
Book a free consultation and get clarity on your loan journey today.
© 2026 Loan Scholar . All Rights Reserved.Designed, Developed & Marketed by
SDS